Institutional Insights: Goldman Sachs 'REGIME SHOCK, FACTOR DRAWDOWN & SYSTEMATIC DE-LEVERAGING'
GLOBAL EQUITIES, DERIVATIVES & FLOW BRIEFING: SHOCKING REGIME, FACTOR DOWNTURN & SYSTEMATIC DE-LEVERAGING
Desk Insights: Institutional Equity Sales Trading & Cross-Asset Volatility Strategy
Data Snapshot: Bloomberg / Desk Data as of Friday, November 6, 2026 (Post-Election Flush & Friday Pre-Market)
THE TAKE: A SYSTEMIC RETEST OF 2020/2025 LOWS AS TECH VALUATIONS PLUMMET
This past week has been a brutal one for global equity markets, culminating in a historic liquidation session that wiped out the gains made after the election and triggered widespread systematic selling programs. While Friday saw signs of stabilization in Asian and European markets—most major markets outside of Japan managed to rise from their opening lows ahead of the Diwali festivities—the previous US cash session left significant structural damage in its wake:
The Nasdaq-100 experienced a staggering drop of -6.36%, closing at 26,629, marking its worst single-day decline since the onset of the pandemic on March 9, 2020, when it fell -6.83%.
The S&P 500 plunged by -4.36% to 7,353, its sharpest one-day drop since the US-China tariff shock on April 4, 2025, which saw a decline of -5.97%.
The Philadelphia Semiconductor Index (SOX) took a nosedive of -12.00%, its worst performance since 2020, compressing forward multiples across the semiconductor sector by approximately 50% from the peaks observed in June and July 2026.
This breakdown signals a fundamental de-risking of post-election data center deployment plans, grid capacity, and the availability of external financing. The rotation that had earlier buoyed the market fell apart completely, with no compensating bids for mega-cap hyperscalers, leaving the entire index vulnerable to programmatic liquidation, as ETF volume surged to 32% of total exchange volume (26.83 billion shares traded).
CROSS-ASSET BENCHMARK SNAPSHOT
- S&P 500 (SPX): Closed at 7,353.00 (-4.36%) | MOC $1.8B to BUY | VIX up +67.19% to 27.77 | Pre-NFP 1-day implied move: 1.43%
- Nasdaq-100 (NDX): Closed at 26,629.00 (-6.36%) | Tech assets liquidated across all tiers
- Russell 2000 (RUT): Closed at 2,729.00 (-4.46%) | Small-cap cyclicals impacted by widespread de-risking
- Dow Jones (DJI): Closed at 51,523.00 (-3.44%) | Value and defensive stocks sold off amid margin calls
- US 10-Year Treasury Yield: Down -5 bps to 4.83% | Flight-to-safety bid steepened at the front end
- WTI Crude: Up +2.80% to $90.58/bbl | Stabilizing around $90 post-election
- Gold: Up +0.57% to $4,084.00/oz | Continuing to attract safe-haven bids
- Bitcoin: Down -5.47% to $75,870.00 | Liquidated alongside high-beta tech assets
- US Dollar Index (DXY): Up +1 bp to 101.58 | Dollar's safe-haven appeal muted by tech unwinds
FACTOR DAMAGE & SYSTEMATIC CTA THRESHOLD BREACHES
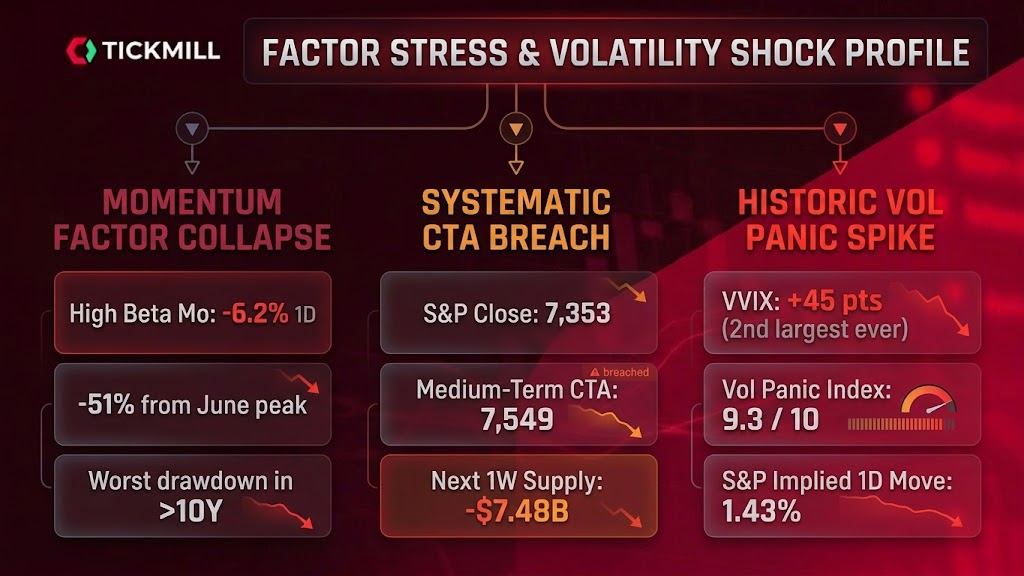
[FACTOR STRESS & VOLATILITY SHOCK PROFILE]
Momentum Factor Collapse | Systematic CTA Breach | Historic Volatility Panic Spike
- High Beta Momentum: -6.2% in one day
- S&P Close: 7,353
- VVIX: +45 points (2nd largest ever)
- Medium-Term CTA: 7,549
- Vol Panic Index: 9.3 / 10
- Next Week Supply: -$7.48B
- S&P Implied 1-Day Move: 1.43%
The High Beta Momentum (GSPRHIMO) factor plummeted by -6.2% in the session, extending its peak-to-trough drawdown to -51% from June highs—the worst decline for this factor in over a decade.
AI Baskets: Several Goldman Sachs pure-play AI baskets recorded their largest single-day drop since the launch of ChatGPT in late 2022.
CTA Model Breach: Futures decisively settled below the medium-term CTA systematic pivot (7,549). Morning model projections indicate an incremental US systematic equity supply of -$7.4 billion...
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!